Saudi Arabia’s payment market has moved faster than many mobile checkout experiences.
Google Pay is now live in the Kingdom through the national mada payment system, giving eligible consumers another fast route from “I want this” to “payment complete.” For businesses, the bigger question is no longer whether Google Pay Saudi Arabia will matter. It is whether their app is ready to turn that payment preference into a faster, cleaner sale.
Google Pay in Saudi Arabia Is No Longer a Future Payment Trend
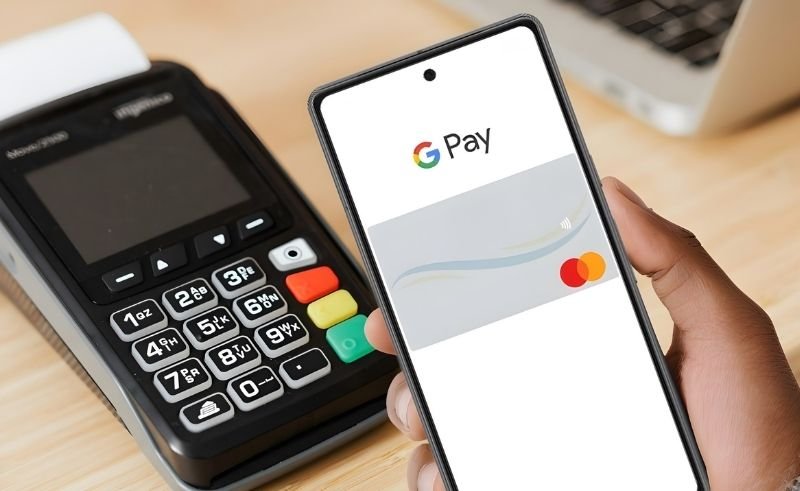
The Saudi Central Bank officially announced the launch of Google Pay in Saudi Arabia on September 15, 2025, through mada. The service allows eligible users to add and manage supported mada and credit cards through Google Wallet and use them for payments.
That launch matters because it arrived in a market where consumers had already moved decisively toward electronic payments.
SAMA reported that electronic payments represented 85% of total retail payment transactions in 2025, compared with 79% in 2024. The number of electronic transactions processed through Saudi national payment systems also increased from 12.6 billion in 2024 to 14.6 billion in 2025.
| Year | Electronic Share of Retail Payments | Electronic Transactions |
| 2023 | 70% | 10.8 billion |
| 2024 | 79% | 12.6 billion |
| 2025 | 85% | 14.6 billion |
The direction is difficult to ignore.
Electronic Share of Saudi Retail Payments
2023 | ███████████████████████████████████ 70%
2024 | ████████████████████████████████████████ 79%
2025 | ███████████████████████████████████████████ 85%
For a business evaluating its next mobile app development company in Saudi Arabia, payment architecture should therefore sit near the beginning of the product conversation, not at the end of development as another checkout button to add before launch.
The Saudi customer has changed. The checkout experience has to change with them.
Digital Payments Saudi Arabia: 85% Changes the Checkout Conversation
When digital payments Saudi Arabia reached 85% of retail payment transactions in 2025, digital checkout stopped being merely a convenience layer. It became part of the core commercial experience.
That creates a different benchmark for apps.
A customer may discover a product in seconds, add it to a basket immediately and then encounter a checkout asking them to manually enter card numbers, expiry dates, billing information and other details they have already stored elsewhere.
Every extra field interrupts momentum.
Imagine ordering dinner while sitting in the back of a car. The app has already remembered your address and previous order. You tap checkout and suddenly face a card form. Your physical wallet is in a bag. The card number is not memorised. The sale that felt effortless three seconds earlier now requires work.
Digital wallets attack that moment of friction.
The objective is not simply to display another payment logo. The objective is to shorten the distance between buying intent and completed payment.
For Saudi retailers, delivery platforms, booking services, marketplaces and other transaction-driven applications, that distinction can directly influence how effectively an app converts demand into revenue.
Mobile Checkout Experience: Your Payment Screen Is Part of the Product
A strong mobile checkout experience should feel like the natural final step of the customer journey rather than a separate financial process.
The best checkout does not make customers think about checkout.
The product has already answered the important questions. The customer knows the item, price, delivery option and total. At that point, the interface should help them authorize the purchase with as little unnecessary interaction as possible.
Google’s Android payment flow reflects that principle. When a customer taps the Google Pay button, a payment sheet can present eligible payment methods saved to their Google Account. After the customer selects a method, Google Pay returns a secure payment token to the application. The app sends that token with the transaction information to its backend, which then passes it to the payment service provider for processing.
That flow removes much of the repetitive input associated with conventional card forms.
It also changes how product teams should evaluate checkout quality. Instead of asking only whether payment technically works, teams should ask how quickly an eligible customer can complete an order, where they have to type, how failures are communicated, whether totals remain clear and how gracefully the experience handles an unavailable payment method.
Checkout is UX. Payment processing is infrastructure. Successful commerce needs both.
Google Pay Integration Saudi Arabia: Think Beyond Adding a Button
A Google Pay integration Saudi Arabia project should begin with the existing payment architecture.
The Google Pay button is the visible part. Behind it sit the payment provider, tokenization configuration, backend transaction handling, order state management, fraud controls, refunds, failed-payment logic and production approval.
That is why adding the logo without reviewing the full transaction flow solves very little.
A product team should first understand where the current payment process breaks down. Users might abandon the checkout after seeing a long card form. Payment success may take too long to confirm. Failed transactions may return vague errors. Customers might accidentally submit twice when the interface appears frozen. The app may create an order before confirming payment or fail to reconcile a successful charge with an interrupted client session.
Integrating Google Pay should improve those flows rather than simply sit beside them.
Businesses planning an iPhone and Android commerce ecosystem may also need a broader mobile payment strategy rather than treating each platform independently. Working with an android app development company in Riyadh should therefore involve discussions around payment orchestration, backend consistency and cross-platform checkout behaviour from the beginning of the project.
Google Pay App Integration and the Actual Payment Flow
For Google Pay app integration, the customer-facing sequence can be remarkably short.
The application checks whether Google Pay is available for the user. When appropriate, it displays the approved Google Pay button. The customer taps it, reviews the payment sheet and selects an eligible payment method. Google Pay then provides the payment token required for the transaction, while the merchant’s backend and payment provider complete the charge.
The simplicity visible to the customer depends on disciplined engineering underneath.
Developers still have to define accepted payment methods, configure tokenization, connect the payment provider, handle transaction status correctly and test the complete purchase journey.
Before production deployment, Google also requires merchants to work through its production process and integration checks. Android applications require production access through the Google Pay & Wallet Console, while the payment architecture needs either an eligible supported payment provider or, for qualifying merchants using direct integration, the required PCI DSS environment.
Where Google Pay Should Appear
Placement affects usefulness.
If a customer can buy a single product directly, an accelerated payment option close to the purchase action may remove unnecessary navigation. In a multi-item cart, Google Pay can become one of the prominent ways to complete checkout after the total is clear.
The important principle is contextual visibility.
Showing a payment option too early can create uncertainty about pricing or delivery. Hiding it after several unnecessary form screens defeats much of its purpose.
The Checkout Should Preserve Context
The customer should never feel transported into an unrelated financial workflow.
The amount, currency and purchase context must remain predictable. A user who taps a SAR 249 purchase button should not need to wonder whether the payment sheet reflects the same order.
Small UX Decisions Influence Trust
Clear totals, immediate feedback, recognisable payment branding and transparent failure states sound minor when considered individually. Together, they shape whether customers feel comfortable pressing “Pay.”
Google Pay Payment Gateway: An Important Technical Distinction
The phrase Google Pay payment gateway appears frequently in payment discussions, but technically Google Pay should not simply be treated as the merchant’s payment gateway.
Google Pay helps the customer select a payment method and securely returns payment credentials in tokenized form. The transaction then moves through the merchant’s backend to its payment service provider or supported gateway for processing. Google’s own documentation describes this separation clearly.
That distinction matters when planning an integration.
If your existing provider supports Google Pay, much of the payment processing relationship remains with that provider. Your development team configures Google Pay to work with the appropriate gateway credentials and transaction flow.
Direct integration is a different architecture. Google states that merchants choosing its Direct tokenization route must meet PCI DSS requirements validated by a Qualified Security Assessor and maintain the infrastructure necessary to securely process payment information.
For many businesses, a supported payment provider is therefore the more practical path.
The decision should come from the merchant’s payment stack, compliance position, acquiring relationships and technical requirements rather than from the checkout interface alone.
Mobile Payment Apps Saudi Arabia Are Competing on Fewer Steps
The next phase of mobile payment apps Saudi Arabia will not be defined only by how many payment methods they display.
The more useful metric is how much effort customers expend between deciding to purchase and receiving confirmation.
Consider two applications selling the same SAR 180 item.
| Checkout Factor | Traditional Card Flow | Wallet-Enabled Flow |
| Card number entry | Often required | Typically avoided for stored eligible cards |
| Expiry/CVV input | Often required | Reduced or avoided in the wallet flow |
| Payment selection | Manual | Saved eligible method presented |
| Mobile typing | Higher | Lower |
| Checkout interruption | Higher potential | Lower potential |
| Customer effort | More steps | Fewer steps |
This is not an argument for removing conventional payment options. Customers still need choice, and card availability varies by bank, card type, device and payment provider.
Google’s current Saudi Wallet support documentation also makes clear that bank and card eligibility can differ. A bank may support certain cards while restricting others, so merchants should not design an experience that assumes every Saudi Android user can automatically pay with Google Wallet.
Good checkout architecture offers acceleration where possible and a clean fallback where it is not.
Contactless Payments Saudi Arabia Have Reset Customer Expectations
Contactless payments Saudi Arabia have influenced more than physical retail.
When customers become accustomed to tapping a device and completing a purchase quickly at a terminal, lengthy digital checkout forms begin to feel increasingly dated.
The psychological benchmark changes.
Customers stop comparing an app only with competing apps in the same industry. They compare its convenience with the fastest transaction experiences they use anywhere.
A grocery application competes with the payment speed customers experience in a café. A hotel booking platform competes with the convenience of a food delivery app. An e-commerce checkout competes with whichever application made the customer’s previous purchase easiest.
This is why payment experience has become a product design issue.
The customer does not care how many systems sit behind a button. They care whether the purchase feels fast, trustworthy and predictable.
E-commerce Payments Saudi Arabia Need More Than Payment Choice
For e-commerce payments Saudi Arabia, adding more logos can create the illusion of checkout optimization.
But five payment methods inside a slow, confusing checkout remain a slow, confusing checkout.
Payment choice only creates value when the surrounding commerce flow supports it.
Product teams should inspect the complete journey from basket to confirmation. Does the application ask for information it already knows? Does it force account creation before purchase? Does a promo-code field distract from payment? Does changing the delivery option unexpectedly reset the checkout? Can the customer clearly see the final amount before authorizing the transaction?
A high-performing payment experience removes avoidable decisions.
That becomes especially important on mobile screens, where every additional field occupies valuable visual space and every keyboard interaction interrupts the purchasing rhythm.
Google Pay can remove a significant part of the payment-input burden, but it cannot repair every weakness around it. Businesses should use integration as an opportunity to redesign the entire checkout rather than patching one new option into an old flow.
Mobile App Payment Integration Should Be Designed Around Failure Too
Successful payments receive most of the attention during mobile app payment integration, yet failed payments often reveal the quality of the product.
A customer might lose connectivity immediately after authorizing a transaction. The processor may approve payment while the app fails to receive the expected client-side response. A user may tap the purchase action twice because the interface provides no progress state. An order could fail internally after the payment succeeds.
These are not edge cases to ignore until customers report them.
The backend should treat transaction state carefully, use reliable identifiers, prevent accidental duplicate processing and reconcile ambiguous situations rather than trusting only what happened on the customer’s screen.
The interface should also tell the customer what is happening.
“Payment failed” is not enough when the system can safely provide a meaningful next action. Neither is leaving an endless spinner after money may already have moved.
Strong commerce applications build trust not only when everything works, but also when something goes wrong.
Is Your App Actually Ready for Google Pay Saudi Arabia?
The right question is not whether your development team can technically add Google Pay.
The question is whether the product is ready to benefit from it.
An app with a slow backend, confusing order flow, weak transaction handling and fragmented checkout will not suddenly become competitive because another wallet button appears.
Start by examining how customers currently buy.
Measure where checkout abandonment occurs. Review the number of required interactions. Inspect payment failures. Test checkout on an actual phone rather than only on a desktop browser or emulator. Compare first-time and returning-customer journeys. Look at what happens after authorization, not just before it.
Then decide where Google Pay removes meaningful friction.
Saudi Arabia’s payment infrastructure is already moving toward increasingly digital behaviour. The commercial opportunity belongs to businesses that translate that infrastructure into better customer experiences rather than simply acknowledging that the technology exists.
FAQs About Google Pay in Saudi Arabia
Is Google Pay available in Saudi Arabia?
Yes. The Saudi Central Bank announced the official launch of Google Pay through the national mada payment system on September 15, 2025.
Does every Saudi bank card work with Google Pay?
No. Support depends on the issuing bank and specific card type. Google maintains a Saudi-specific page showing supported banks and cards and notes that issuers can restrict particular cards from mobile payments.
Can Saudi businesses add Google Pay to an Android app?
Businesses can integrate the Google Pay API into eligible applications when their payment architecture and provider support the required flow. Production deployment also requires completing Google’s relevant integration and approval requirements.
Is Google Pay itself a payment gateway?
Not in the conventional merchant-processing sense. Google Pay provides tokenized payment information that the merchant’s backend passes to an appropriate payment service provider or gateway for transaction processing.
Can Google Pay be used for website checkout as well?
Yes. Google provides a Web API in addition to its Android integration. On the web, eligible customers can select payment methods saved to their Google Account, after which the website sends the returned payment token through its backend for processing.
Does adding Google Pay automatically improve conversion?
No payment method guarantees higher conversion. Google Pay can remove payment-entry friction for eligible customers, but checkout performance still depends on pricing clarity, speed, UX, payment reliability, account requirements, delivery options and the rest of the purchase flow.
The Payment Infrastructure Is Ready. Your Checkout Should Be Too.
Google Pay arriving in Saudi Arabia is not important because businesses gained one more logo to place beside a card form. It matters because Saudi consumers are operating inside an increasingly mature digital payment economy, while the standard for a convenient purchase continues to rise.
The strongest applications will connect payment choice with thoughtful product design, resilient transaction architecture and a checkout that respects the customer’s time. If your current app still makes customers work harder than necessary to complete a purchase, now is the right moment to review the journey, remove friction and build a payment experience designed for the way Saudi customers increasingly buy. Businesses ready to modernize that experience can work with codhaus to design and develop mobile commerce applications in which payment is not an afterthought, but a natural part of the product.
Disclaimer: The information provided in this article is for general informational and educational purposes only. It does not constitute professional technical, financial, or legal advice. Payment regulations, integration requirements, and platform features may change. Readers should verify current guidelines with the Saudi Central Bank, Google Pay documentation, and qualified payment providers. The mention of codhaus or any specific company is illustrative and does not imply endorsement. The author and publisher disclaim all liability for integration issues, transaction failures, or financial losses arising from reliance on this content. Always test payment flows thoroughly and comply with applicable PCI DSS and regulatory requirements.
Discover posts that turn questions into answers—our solution-oriented content gives you clarity where it counts.